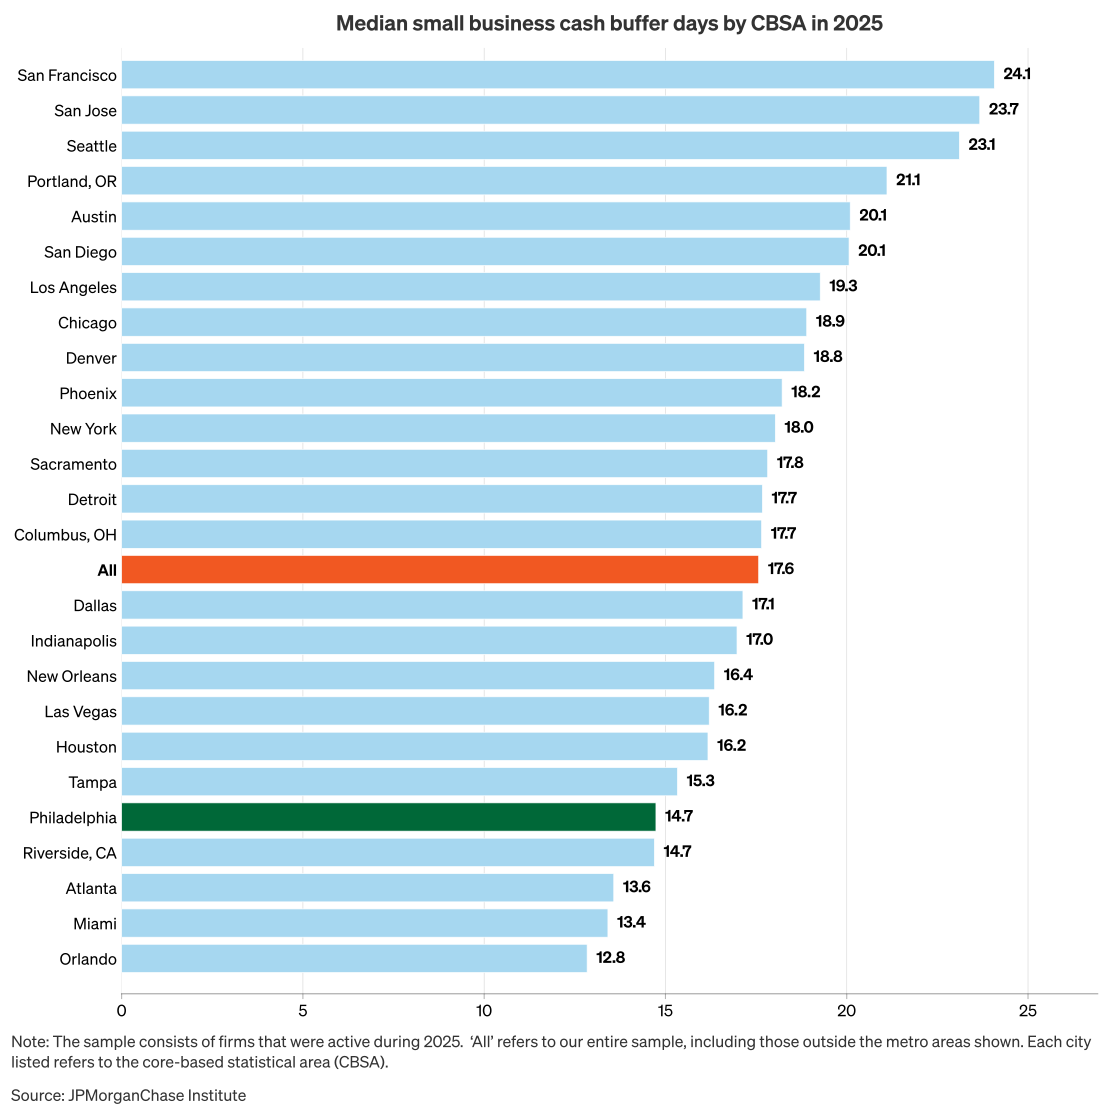
Figure 1: Philadelphia small businesses held smaller cash buffers than the overall median firm.
Creating thriving communities together
See how our clients and partners—from small business owners to workforce training leaders—work with JPMorganChase to drive meaningful impact and economic growth where they live and work.
Learn moreLatest news
Veteran’s Unconventional Path to Landing her Dream Job in Tech
U.S. Army Veteran Ashley Wigfall transitioned to a civilian role and charted her path to technologist through mentorship and skills training at the JPMorgan Chase tech hub in Plano, Texas.
Learn more
Research
October 27, 2026
The Philadelphia metro area — spanning parts of Pennsylvania, New Jersey, and Delaware — is home to more than 628,000 small businesses. Small businesses accounted for 46 percent of employment in the region, with the largest number of employees in the health care and social assistance industry. (U.S. Small Business Administration 2025b).1
We analyzed 2.1 million small businesses with Chase Business Banking accounts operating during 2025,2 including 14,000 in the Philadelphia metro area,3 to provide a snapshot of their financial health. The typical small business in Philadelphia exhibits financial health measures—14.7 cash buffer days and $115,900 in annual revenues—that are more modest than those of a typical small business in the U.S. Despite this, there are differences by industry, with wholesale trade and information showing relatively stronger revenues than the overall sample.
Cash buffer days: Small businesses may differ along many dimensions, such as size, industry, location, and growth trajectories, but they all need to manage their cash flows. Cash reserves can be used not only to absorb unexpected shortfalls in revenue or increases in expenses but also to invest in growth opportunities. We use cash buffer days to measure how long a small business could maintain its average outflows in the event of a complete disruption to inflows.4
Figure 1 shows the median cash buffer days for small businesses across 25 metro areas. The typical firm in our nationwide sample held 17.6 cash buffer days in 2025, indicating that its cash reserves could sustain its average outflows for over 17 days. The typical small firm in Philadelphia held 14.7 cash buffer days, suggesting a more limited ability to absorb economic shocks compared to the overall median.
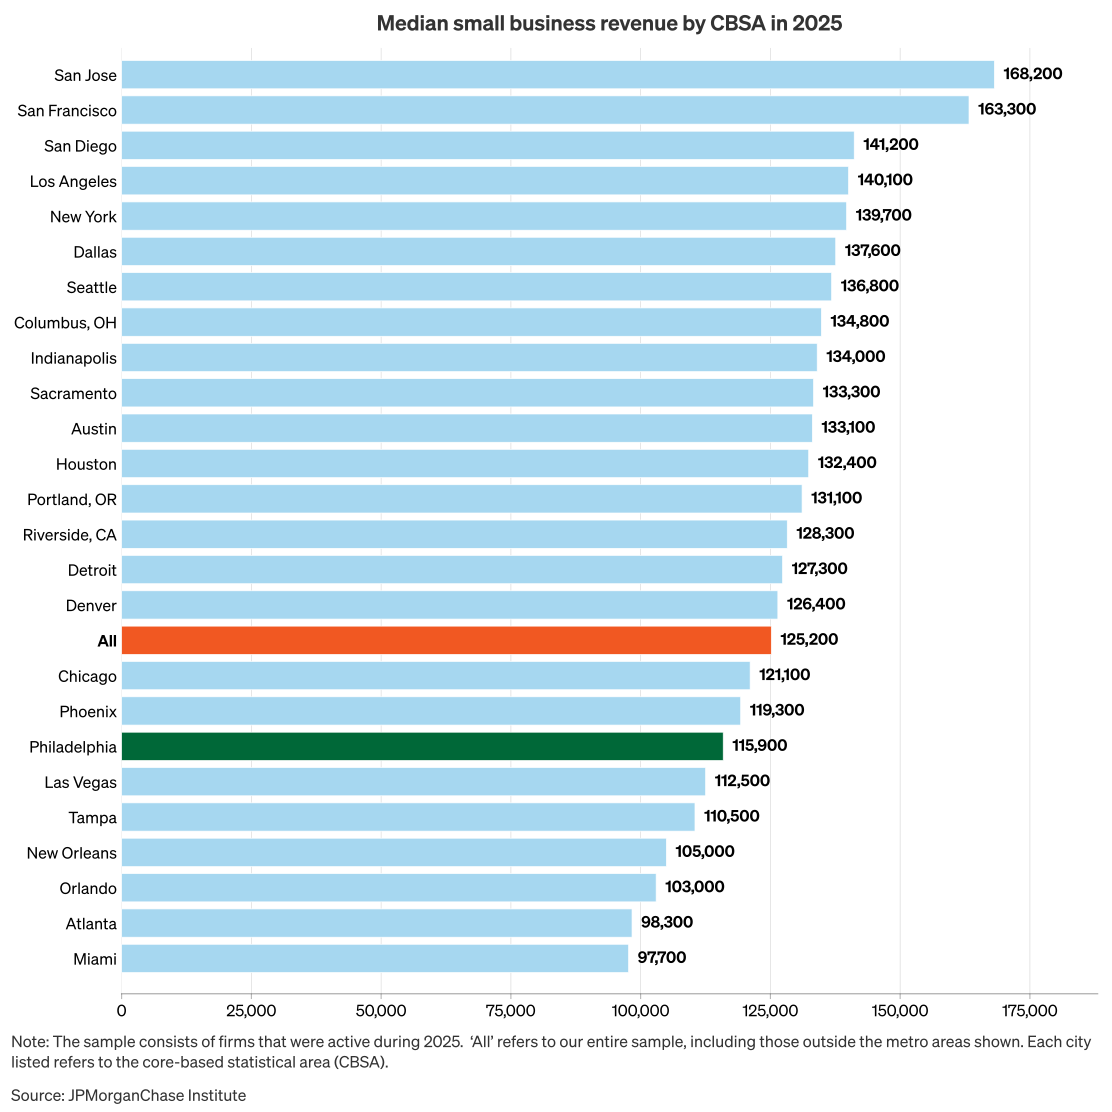
Revenues: Revenue is another important measure of firm financial health. Figure 2 shows the median annual revenues for 25 metro areas. Across our sample, the median small business generated $125,200 in revenues during 2025. In the Philadelphia metro area, median revenue was somewhat lower, at $115,900. Typical revenues may vary by industry, so the composition of the small business sector within a metro area could affect the median.
In the Philadelphia metro area, professional services had the most small businesses, while health care and social assistance employed the most people. A larger share of Philadelphia's small businesses is engaged in professional services: 16 percent in Philadelphia compared to 13 percent nationwide.5
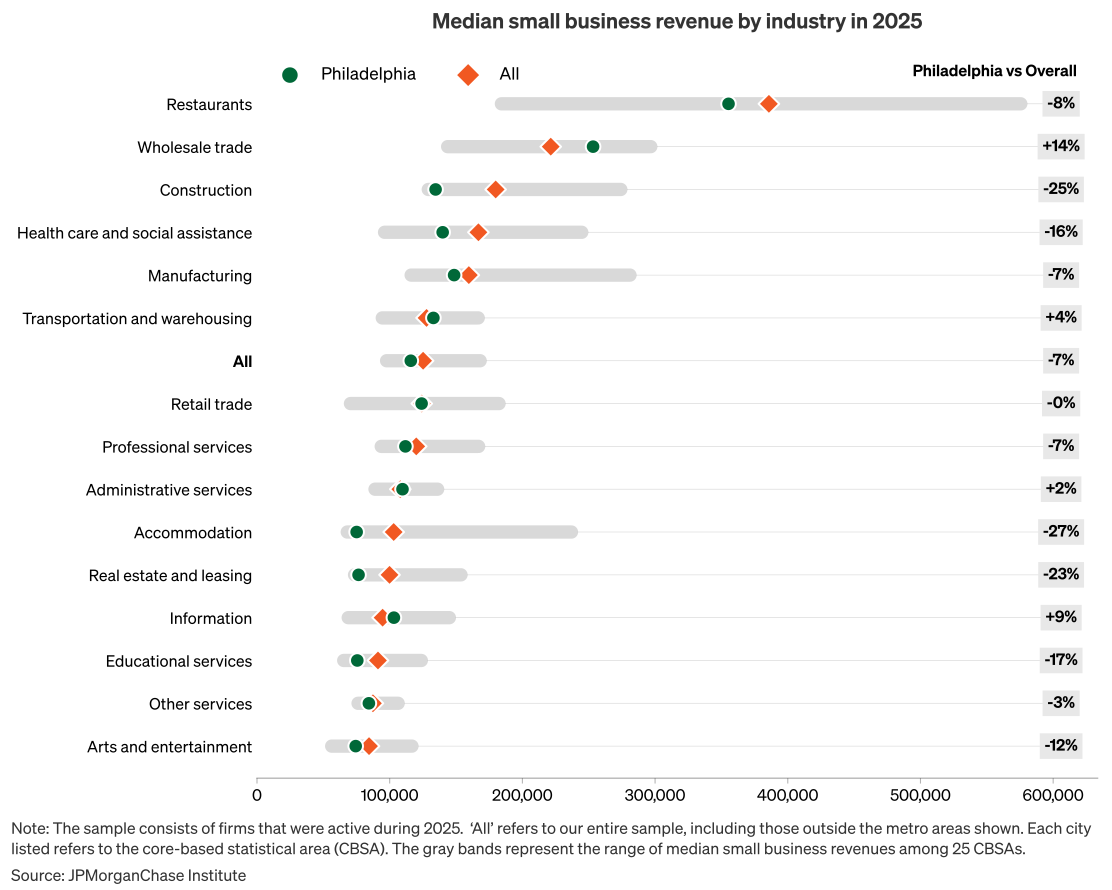
Figure 3 shows the median annual revenues in 2025 by industry for Philadelphia, relative to the median in our overall sample, as well as the range of median revenues across 25 metro areas. Across most industries, small business revenues in Philadelphia were somewhat lower than in the overall sample. Small professional service firms in Philadelphia earned revenues that were 7 percent lower than those in our overall sample, and health care and social assistance—the metro's largest employer—trailed by 16 percent. Restaurants had the highest median revenues across industries in Philadelphia, though revenues there were still 8 percent lower than the overall sample.6 Wholesale trade was the clearest exception, with revenues 14 percent higher than the overall sample.
Taken together, the median cash buffer days and revenues suggest that small businesses in Philadelphia exhibit somewhat more modest measures of financial health than the typical small firm elsewhere in the U.S. That said, Philadelphia's small businesses had higher revenues the overall sample in the wholesale trade and information industries.
Farrell, Diana, Chris Wheat, Chi Mac, and Bryan Kim. 2020. “Small Business Expenses during COVID-19.” JPMorganChase Institute. https://www.jpmorganchase.com/institute/all-topics/business-growth-and-entrepreneurship/report-small-business-expenses-during-COVID-19.
U.S. Small Business Administration, Office of Advocacy. 2025a. “2025 Small Business Profile, United States.” Accessed September 14, 2026. https://advocacy.sba.gov/wp-content/uploads/2025/06/United_States_2025-State-Profile.pdf.
U.S. Small Business Administration, Office of Advocacy. 2025b. “Small Business Profiles for Major Metropolitan Areas of the Northeast 2025.” Accessed September 14, 2026. https://advocacy.sba.gov/wp-content/uploads/2025/10/Northeast_2025_FINAL.pdf.
This material is a product of JPMorganChase Institute and is provided to you solely for general information purposes. Unless otherwise specifically stated, any views or opinions expressed herein are solely those of the authors listed and may differ from the views and opinions expressed by J.P. Morgan Securities LLC (JPMS) Research Department or other departments or divisions of JPMorgan Chase & Co. or its affiliates. This material is not a product of the Research Department of JPMS. Information has been obtained from sources believed to be reliable, but JPMorgan Chase & Co. or its affiliates and/or subsidiaries (collectively J.P. Morgan) do not warrant its completeness or accuracy. Opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which is provided for illustration/reference purposes only. The data relied on for this report are based on past transactions and may not be indicative of future results. J.P. Morgan assumes no duty to update any information in this material in the event that such information changes. The opinion herein should not be construed as an individual recommendation for any particular client and is not intended as advice or recommendations of particular securities, financial instruments, or strategies for a particular client. This material does not constitute a solicitation or offer in any jurisdiction where such a solicitation is unlawful.
We are thankful to the many people who made essential contributions to this research, especially Michael Vaden for exceptional research assistance and Sarwari Das for project management. We are also indebted to our internal partners and colleagues, who support delivery of our agenda in a myriad of ways and acknowledge their contributions to each release.
JPMorganChase Institute. 2026. “Small business snapshot: Philadelphia.” https://www.jpmorganchase.com/institute/all-topics/business-growth-and-entrepreneurship/philadelphia-small-business-snapshot
Philadelphia area data is reported for the Philadelphia-Camden-Wilmington metropolitan area in 2022, the most recent available from the U.S. Census Bureau.
Our sample includes small firms with no more than three deposit accounts that were open during the entire 2025 calendar year and active, with at least 10 transactions and $500 in outflows, in at least three months. To ensure that these firms were small, we limited the sample to firms operating in one ZIP code and one industry.
Throughout this brief, we use the Core Based Statistical Area (CBSA) for Philadelphia but may refer to the area simply as Philadelphia for brevity.
During times of distress, small businesses may pull back expenses, possibly to preserve liquidity. For example, during the COVID-19 pandemic, expense growth mirrored the reduced revenue growth small businesses experienced due to operating restrictions and lower demand (Farrell et al. 2020).
There were 97,492 small businesses in professional services in Philadelphia, out of a total of 628,755. Nationwide, there were 4,881,738 small businesses in professional services, out of a total of 36,186,089 small firms (U.S. Small Business Administration 2025a, 2025b). This industry corresponds to two-digit NAICS code 54 and is also known as professional, scientific, and technical services.
Small businesses in accommodation and food services employed 143,427 people in Philadelphia in 2022, the second largest after health care and social assistance (U.S. Small Business Administration 2025b). In Figure 3, we split out restaurants (food services) and accommodation to highlight differences in these sectors.
Media Contact
Shelby Wagenseller,
shelby.wagenseller@jpmchase.com