This summer, the European Commission took an important step toward a forward-looking agenda to strengthen competitiveness in one of Europe’s most critical sectors — banking — by publishing a landmark report that sets out its vision. With the Commission's report on banking competitiveness now on the table, and legislative choices to follow, Europe is once again asking how its financial system can best serve its economy. Now is the time to focus on the foundational question: what is finance actually for?

Our answer is straightforward. A competitive banking sector is a strategic enabler for the wider European economy. It can provide essential financing with broad reach – helping Europe retain its international edge in core industries, strengthen defence and resilience capabilities in the face of growing geopolitical threats. It can also support competitiveness in the industries of the future, including technology, AI, and renewable energy.

Read through that lens, the Commission's report asks many of the right questions. If Europe wants to strengthen competitiveness across the wider economy, it must allow its banks to build the capacity to finance it.

Three choices now on the table matter most for breaking the barriers that stand in the way of unifying and supercharging Europe’s banking sector at scale:

  1. The first and one of the most important choices is taking a full-throated, ambitious approach to unifying fragmented markets. For European banks to grow, compete globally, and serve clients well, the Single Market needs to live up to the name in practice, not just in principle. The Single Market remains one of the most ambitious economic projects in the world, and the steady work of integration through the Banking Union and the emerging Savings and Investments Union is not an abstract policy goal. Europe needs to develop more of this capability, yet national frictions still fragment its markets. Understandably, the EU brings together sovereign nations with thousands of years of rich histories and a diverse set of cultures. Each Member State has its own complex economic backgrounds and business traditions, and each adds unique value to the EU. A Single Market should respect that diversity, while reducing the barriers that prevent capital and services from flowing freely to where they are most needed. The European Commission’s proposed corporate legal framework, the 28th regime, often described as “EU Inc.,” is a good example of the type of ambitious reforms needed to enable companies to start up, grow, and operate across Member States. But it should not stop there. The Commission should build on this momentum by working with Member States to address other sources of friction to companies operating across borders, like fragmented insolvency laws.

    Member States already know that when the European Union acts as one, it can achieve far more than any individual state can accomplish alone. If a true Single Market in every sense of the word would ever be achieved, everyone in the region would have a lot to gain. It could allow companies to raise capital seamlessly across all Member States. It could also deliver EU-wide interoperability in payments and critical digital technologies so consumers and businesses can operate cross-border as easily as domestically. Additionally, it could leverage that openness to establish strategic infrastructure across the EU — an integrated energy grid, cross-border climate resilience, digital connectivity, integrated transport networks that cut cost, and more. We must work together to deliver on the promises of a Single Market; transforming that principle into tangible reality would enable companies to scale and deliver growth for the benefit of all EU consumers.

If Europe wants to strengthen competitiveness across the wider economy, it must allow its banks to build the capacity to finance it.

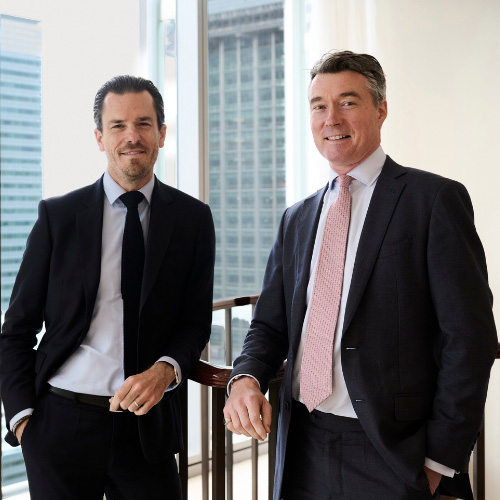
Matthieu Wiltz and Conor Hillery

  1. The second is risk-based banking supervision. A resilient banking system is the foundation for everything else. However, resilience and competitiveness aren’t a zero-sum, either/or game. The Commission's signals here — a shift toward a more risk-based culture — point in the right direction. Risk-based supervision will remove another source of regulatory friction that imposes operational burden without enhancing resilience. In particular, it would help reduce the proliferation of supervisory “soft law” practices that add to that burden by layering new expectations onto existing requirements. This shift could strengthen banks’ ability to factor requirements into their business planning with confidence, allow banks to better respond to businesses and markets at the speed they actually move, and enable European banks to better compete.
  2. The third is regulatory consistency and nimbleness. Europe's banking rulebook has grown dense and inconsistent. This in turn slows the flow of business and diverts management focus and resources away from serving clients and financing the real economy into compliance tasks, which increase the cost of capital across the economy.


Simplifying these rules is, rightly, one of the priorities included by the Commission in its report. Making the rulebook fit to deliver EU competitiveness will require the streamlining of existing rules and more balanced approach to the design of new ones in the future. Done well, simplification could deliver the combined benefits of retaining the safeguards that ensure financial stability and building European competitiveness amid emerging threats and shifting opportunities.

This is not a challenge for EU institutions alone. As a firm that has been part of the European economy for generations, J.P. Morgan’s focus on Europe is not conditional on any single reform. We invest in Europe, we lend in Europe, and we see ourselves as a partner in building a deeper, better-integrated Single Market. We are not a spectator offering advice from the sidelines.

Our team speaks from experience. We have deep expertise in the business of scaling — supporting innovative, venture-backed startups as they mature into mid-sized companies and ultimately scale into large-cap corporations. Across each stage of that journey, we help clients navigate growth by providing corporate finance, cash management, payments, and foreign exchange services — capabilities that enable them to invest, create jobs, and contribute to the wider economy.

And while it may seem counterintuitive, we support the growth of local and regional banks because it serves the long-term interests of Europe and its people, which ultimately benefits everyone who operates here. We are not shy in saying that includes us. European banks of all sizes should be able to scale. Achieving this outcome would be a clear sign that the EU’s competitiveness project has delivered healthy competition and an investable, efficient banking system — one that strengthens the EU economy and supports the businesses, households, and investors who depend on a resilient financial system.

The decisions that follow in the months ahead will help set the direction. We look forward to being part of them — and to keeping the focus where it belongs: on a financial system that does its most important job to finance and scale the real economy on which everyone in the region depends.
This material has not been reviewed, endorsed, or otherwise approved by, and is not a work product of, any research department of JPMorganChase & Co. and/or its affiliates. Information contained in this document has been obtained from sources, including those publicly available, believed to be reliable, but no representation or warranty is made by the document’s author or JPMorganChase as to the quality, completeness, accuracy, fitness for a particular purpose or non-infringement of such information. Sources of third-party information referred to herein retain all rights with respect to such data and use of such data by JPMorganChase herein shall not be deemed to grant a license to any third party. All information contained herein is as of the date referenced and is subject to change without notice.